Deterministic Underwriting Architecture
Deterministic Underwriting Architecture
Deterministic Underwriting Architecture
Every policy decision is a logic tree...
Every policy decision is a logic tree...
Every policy decision is a logic tree...
Every institutional capital allocation is governed by strict deterministic logic. Yet, most financial firms operate with fragmented, undocumented risk parameters. Below are five architectural blueprints demonstrating how complex underwriting gates, from evaluating SEC 10-K supply chain vulnerabilities to baseline credit thresholds, are codified into executable infrastructure. This is the critical Model Risk Management (MRM) layer that probabilistic AI projects fundamentally lack.
Every institutional capital allocation is governed by strict deterministic logic. Yet, most financial firms operate with fragmented, undocumented risk parameters. Below are five architectural blueprints demonstrating how complex underwriting gates, from evaluating SEC 10-K supply chain vulnerabilities to baseline credit thresholds, are codified into executable infrastructure. This is the critical Model Risk Management (MRM) layer that probabilistic AI projects fundamentally lack.
Every institutional capital allocation is governed by strict deterministic logic. Yet, most financial firms operate with fragmented, undocumented risk parameters. Below are five architectural blueprints demonstrating how complex underwriting gates, from evaluating SEC 10-K supply chain vulnerabilities to baseline credit thresholds, are codified into executable infrastructure. This is the critical Model Risk Management (MRM) layer that probabilistic AI projects fundamentally lack.
Feelistic Studio built on industry standards
Feelistic Studio built on industry standards
Feelistic Studio built on industry standards
AI is a black box, we provide the underlying logic.
AI is a black box, we provide the underlying logic.
AI is a black box, we provide the underlying logic.
Each blueprint is a regulator-ready DMN (Decision Model and Notation) asset: translating subjective risk policies into fully auditable Decision Requirements Diagrams governed by strict FEEL (Friendly Enough Expression Language) execution tables.
Each blueprint is a regulator-ready DMN (Decision Model and Notation) asset: translating subjective risk policies into fully auditable Decision Requirements Diagrams governed by strict FEEL (Friendly Enough Expression Language) execution tables.
Each blueprint is a regulator-ready DMN (Decision Model and Notation) asset: translating subjective risk policies into fully auditable Decision Requirements Diagrams governed by strict FEEL (Friendly Enough Expression Language) execution tables.
Decision (rule table)
Decision (rule table)
Decision (rule table)
Input data
Input data
Input data
Information requirement
Information requirement
Information requirement
Term Life Underwriting
Male, 45 · HK$5M term life coverage · Non-smoker
DECISION REQUIREMENTS DIAGRAM

BUSINESS RULES DECISION TABLES

Term Life Underwriting
Male, 45 · HK$5M term life coverage · Non-smoker
DECISION REQUIREMENTS DIAGRAM
BUSINESS RULES DECISION TABLES
Term Life Underwriting
Male, 45 · HK$5M term life coverage · Non-smoker
DECISION REQUIREMENTS DIAGRAM
BUSINESS RULES DECISION TABLES
HOW THIS MODEL WORKS - IN PLAIN ENGLISH
HOW THIS MODEL WORKS - IN PLAIN ENGLISH
1
1
How the flow works
How the flow works
How the flow works
The three rounded boxes are facts we collect: smoking status, occupation class, total cholesterol. Cholesterol flows first into Evaluate Lipid Flag, a small decision that checks the reading against the insurer’s medical guideline (3.2) and returns Triggered or Clear. We isolate it so the threshold changes in one place. That verdict, with smoking status and occupation, feeds Determine UW Outcome, the underwriting rulebook as a table.
This applicant gets standard cover with a retest booked: exactly what a human underwriter would decide, in milliseconds, with the reasoning written down.
2
2
Who does what? The Roles & Interaction
Who does what? The Roles & Interaction
Who does what? The Roles & Interaction
The model does not replace people; it captures the logic they already apply and routes the genuine exceptions back to them.
The model does not replace people; it captures the logic they already apply and routes the genuine exceptions back to them.
Senior / Chief Underwriter: Owns the rulebook. Signs off the thresholds and loadings in the Determine UW Outcome table, these are their rules, made explicit.
Senior / Chief Underwriter: Owns the rulebook. Signs off the thresholds and loadings in the Determine UW Outcome table, these are their rules, made explicit.
Senior / Chief Underwriter: Owns the rulebook. Signs off the thresholds and loadings in the Determine UW Outcome table, these are their rules, made explicit.
Medical Officer: Owns the medical thresholds in Evaluate Lipid Flag (e.g. the 5.2 lipid cut-off and which guideline it cites).
Medical Officer: Owns the medical thresholds in Evaluate Lipid Flag (e.g. the 5.2 lipid cut-off and which guideline it cites).
Medical Officer: Owns the medical thresholds in Evaluate Lipid Flag (e.g. the 5.2 lipid cut-off and which guideline it cites).
Underwriter (frontline): Stops touching the 80% of clean cases the model auto-issues; spends time only on the “refer” cases the model escalates.
Underwriter (frontline): Stops touching the 80% of clean cases the model auto-issues; spends time only on the “refer” cases the model escalates.
Underwriter (frontline): Stops touching the 80% of clean cases the model auto-issues; spends time only on the “refer” cases the model escalates.
Actuarial & Product: Sees every decision as structured data, so pricing and loadings can be tested against real outcomes.
Actuarial & Product: Sees every decision as structured data, so pricing and loadings can be tested against real outcomes.
Actuarial & Product: Sees every decision as structured data, so pricing and loadings can be tested against real outcomes.
Compliance: Gets a complete, time-stamped record of why each policy was issued, the auditable trail HKMA AI governance expects.
Compliance: Gets a complete, time-stamped record of why each policy was issued, the auditable trail HKMA AI governance expects.
Compliance: Gets a complete, time-stamped record of why each policy was issued, the auditable trail HKMA AI governance expects.
3
3
How do we build it? The Elicitation Process
How do we build it? The Elicitation Process
How do we build it? The Elicitation Process
“Elicitation” simply means getting the rules out of people’s heads and documents and into the table. For this model we:
“Elicitation” simply means getting the rules out of people’s heads and documents and into the table. For this model we:
“Elicitation” simply means getting the rules out of people’s heads and documents and into the table. For this model we:
Run short workshops with the senior underwriter and medical officer, walking real past cases to surface the actual thresholds they use.
Mine the underwriting manual, reinsurer treaty terms and exception logs, most rules already exist in writing, just scattered across two or three places.
Draft each rule as a plain “When… Then…” row, then play it back to the experts for confirmation before it goes live.
Capture the source (e.g. “Guideline 3.2”) in the Annotations column so every rule is traceable to its authority.
4
4
The benefits
The benefits
The benefits
Faster, consistent decisions - clean applications issue instantly; two underwriters can no longer reach two different answers on the same facts.
No black box - the reasoning is a readable table, not hidden in code or someone’s experience.
Change once, apply everywhere - adjust a threshold in the table and every future decision uses it immediately.
Regulator-ready - each decision produces an explainable, logged audit trail aligned with HKMA principles and PDPO accountability.
5
5
Next steps: what this unlocks
Next steps: what this unlocks
Next steps: what this unlocks
Connect to InvestLM or your AI platform - these structured rules (exportable as DMN/FEEL) can be ingested so the AI reasons with your risk appetite, not generic logic.
Add an interactive demo - let a prospect change the cholesterol value on the website and watch the outcome update live.
Extend the rulebook - layer in more medical, financial and occupational rules without rebuilding anything; each is just another row.
Straight-through processing - once confidence is proven on Standard cases, widen the auto-issue band and measure the reduction in manual review time.
AML Transaction Monitoring
Male, 52 · HK resident · corporate account · incoming wire HK$4.8M
DECISION REQUIREMENTS DIAGRAM

BUSINESS RULES DECISION TABLES

AML Transaction Monitoring
Male, 52 · HK resident · corporate account · incoming wire HK$4.8M
DECISION REQUIREMENTS DIAGRAM
BUSINESS RULES DECISION TABLES
AML Transaction Monitoring
Male, 52 · HK resident · corporate account · incoming wire HK$4.8M
DECISION REQUIREMENTS DIAGRAM
BUSINESS RULES DECISION TABLES
HOW THIS MODEL WORKS - IN PLAIN ENGLISH
HOW THIS MODEL WORKS - IN PLAIN ENGLISH
1
1
How the flow works
How the flow works
How the flow works
We collect three facts about the customer and the wire: PEP status, typical monthly volume, and the risk rating of the jurisdiction the money came from. Two decisions follow. Determine High-Risk Jurisdiction checks the source country against the bank’s list. Calculate Risk Flag combines everything: a PEP, a high-risk jurisdiction, or volume above HK$100,000 flags the customer High; otherwise, Medium.
The top decision, determine EDD Requirement, sets the consequence. For this HK$4.8M wire from a high-risk jurisdiction, the chain fires, the transaction is held, and enhanced due diligence begins with senior approval and a source-of-wealth check. Every step is recorded.
2
2
Who does what? The Roles & Interaction
Who does what? The Roles & Interaction
Who does what? The Roles & Interaction
The model does not replace people; it captures the logic they already apply and routes the genuine exceptions back to them.
The model does not replace people; it captures the logic they already apply and routes the genuine exceptions back to them.
The model does not replace people; it captures the logic they already apply and routes the genuine exceptions back to them.
Relationship Manager (1st line): Provides the customer facts (PEP status, expected volumes) at onboarding. The model tells them instantly when a wire needs to pause.
Relationship Manager (1st line): Provides the customer facts (PEP status, expected volumes) at onboarding. The model tells them instantly when a wire needs to pause.
Relationship Manager (1st line): Provides the customer facts (PEP status, expected volumes) at onboarding. The model tells them instantly when a wire needs to pause.
AML Analyst (2nd line): Works only the cases the model flags for EDD, with the required actions already listed, no more manually triaging every transaction.
AML Analyst (2nd line): Works only the cases the model flags for EDD, with the required actions already listed, no more manually triaging every transaction.
AML Analyst (2nd line): Works only the cases the model flags for EDD, with the required actions already listed, no more manually triaging every transaction.
MLRO / Compliance: Owns the rules, the high-risk list, the HK$100k threshold, the score > 7 cut-off. These are policy decisions, now written as editable table rows.
MLRO / Compliance: Owns the rules, the high-risk list, the HK$100k threshold, the score > 7 cut-off. These are policy decisions, now written as editable table rows.
MLRO / Compliance: Owns the rules, the high-risk list, the HK$100k threshold, the score > 7 cut-off. These are policy decisions, now written as editable table rows.
Senior Management: Named explicitly in the output (“Senior Approval”) so the sign-off step is built into the decision, not bolted on afterwards.
Senior Management: Named explicitly in the output (“Senior Approval”) so the sign-off step is built into the decision, not bolted on afterwards.
Senior Management: Named explicitly in the output (“Senior Approval”) so the sign-off step is built into the decision, not bolted on afterwards.
Internal Audit (3rd line): Reads the logged trail to prove the monitoring worked exactly as the policy intended.
Internal Audit (3rd line): Reads the logged trail to prove the monitoring worked exactly as the policy intended.
Internal Audit (3rd line): Reads the logged trail to prove the monitoring worked exactly as the policy intended.
3
3
How do we build it? The Elicitation Process
How do we build it? The Elicitation Process
How do we build it? The Elicitation Process
We turn the AML rulebook that lives in policy documents and analysts’ judgement into explicit, testable rules:
We turn the AML rulebook that lives in policy documents and analysts’ judgement into explicit, testable rules:
We turn the AML rulebook that lives in policy documents and analysts’ judgement into explicit, testable rules:
Workshop with the MLRO and senior AML analysts to capture the real triggers they act on day to day.
Map each trigger to its source, the HKMA AML/CFT Guideline, sanctions/PEP screening lists and the firm’s internal risk appetite.
Review a sample of past alerts and filed SARs to confirm the thresholds reproduce the decisions analysts actually made.
Validate the draft tables with Compliance, then version-control them so every change to a threshold is itself auditable.
4
4
The benefits
The benefits
The benefits
Consistent risk decisions - the same facts always produce the same flag, removing analyst-to-analyst variation regulators dislike.
Faster clearing of low-risk traffic - analysts focus on genuine high-risk cases instead of clearing noise.
Actions built in - the model doesn’t just flag risk, it states what must happen next (approval, source-of-wealth check).
Defensible & explainable - a full HKMA/IA-ready trail showing why each transaction was held or cleared.
5
5
Next steps: what this unlocks
Next steps: what this unlocks
Next steps: what this unlocks
Live transaction screening - wire this decision service into the payment flow so wires are scored in real time.
Feed an AI investigator - structured outputs let InvestLM or an agent draft the EDD narrative and SAR with full traceability.
Tune with data - because every decision is logged, thresholds can be calibrated against false-positive rates over time.
Reuse the pattern - the same DRD shape extends to sanctions screening, fraud and trade surveillance with new rule rows.
Group Health Claims Pre-authorisation
Female, 41 · corporate group health · MRI spine (orthopaedic referral)
DECISION REQUIREMENTS DIAGRAM

BUSINESS RULES DECISION TABLES

Group Health Claims Pre-authorisation
Female, 41 · corporate group health · MRI spine (orthopaedic referral)
DECISION REQUIREMENTS DIAGRAM
BUSINESS RULES DECISION TABLES
Group Health Claims Pre-authorisation
Female, 41 · corporate group health · MRI spine (orthopaedic referral)
DECISION REQUIREMENTS DIAGRAM
BUSINESS RULES DECISION TABLES
HOW THIS MODEL WORKS - IN PLAIN ENGLISH
HOW THIS MODEL WORKS - IN PLAIN ENGLISH
1
1
How the flow works
How the flow works
How the flow works
From the bottom up, we collect four facts about a pre-authorisation request: the procedure code (here an MRI spine), the policy limit remaining, the amount requested, and the member’s claims history over the last 24 months.
The two money facts feed a small decision, Check Policy Limit, which answers one yes/no question: is the requested amount within the remaining limit? Keeping this separate means finance can change limit logic without disturbing the clinical rules.
That yes/no, together with specialist eligibility (from the procedure code) and a clean claims history, flows into Determine Pre-auth Outcome. If all three hold true, the request is “Approved” within the service-level target, under four business hours with the standard 10% co-pay applied. If any one fails, it routes to “Manual review” for a human assessor. The example request, an in-network MRI, well within limit, clean history, approves automatically and notifies member and provider, with a full decision log written for audit.
2
2
Who does what? The Roles & Interaction
Who does what? The Roles & Interaction
Who does what? The Roles & Interaction
The model clears the routine approvals so skilled assessors spend their time on the cases that genuinely need a human eye.
The model clears the routine approvals so skilled assessors spend their time on the cases that genuinely need a human eye.
The model clears the routine approvals so skilled assessors spend their time on the cases that genuinely need a human eye.
Claims Assessor: Stops rubber-stamping clear-cut approvals; handles only the “Manual review” cases the model can’t safely auto-approve.
Claims Assessor: Stops rubber-stamping clear-cut approvals; handles only the “Manual review” cases the model can’t safely auto-approve.
Claims Assessor: Stops rubber-stamping clear-cut approvals; handles only the “Manual review” cases the model can’t safely auto-approve.
Medical Officer: Owns the clinical rules, which procedures sit on the approved specialist list and what counts as a clean history.
Medical Officer: Owns the clinical rules, which procedures sit on the approved specialist list and what counts as a clean history.
Medical Officer: Owns the clinical rules, which procedures sit on the approved specialist list and what counts as a clean history.
Provider Network Team: Maintains the specialist list that drives eligibility; updates flow straight into the decision.
Provider Network Team: Maintains the specialist list that drives eligibility; updates flow straight into the decision.
Provider Network Team: Maintains the specialist list that drives eligibility; updates flow straight into the decision.
Finance / Actuarial: Owns the limit and co-pay logic in Check Policy Limit, and sees utilisation as structured data.
Finance / Actuarial: Owns the limit and co-pay logic in Check Policy Limit, and sees utilisation as structured data.
Finance / Actuarial: Owns the limit and co-pay logic in Check Policy Limit, and sees utilisation as structured data.
Customer Service: Can tell a member instantly whether a procedure is pre-approved, with the SLA committed upfront.
Customer Service: Can tell a member instantly whether a procedure is pre-approved, with the SLA committed upfront.
Customer Service: Can tell a member instantly whether a procedure is pre-approved, with the SLA committed upfront.
Compliance: Holds a complete claims decision log supporting PDPO accountability and explainability.
Compliance: Holds a complete claims decision log supporting PDPO accountability and explainability.
Compliance: Holds a complete claims decision log supporting PDPO accountability and explainability.
3
3
How do we build it? The Elicitation Process
How do we build it? The Elicitation Process
How do we build it? The Elicitation Process
We extract the pre-authorisation rules from the policy and the assessors who apply them:
We extract the pre-authorisation rules from the policy and the assessors who apply them:
We extract the pre-authorisation rules from the policy and the assessors who apply them:
Workshop with senior claims assessors and the medical officer to capture the real approve/refer thresholds.
Translate the policy wording, group claims protocol and specialist list into explicit “When… Then…” rows.
Replay a batch of recent pre-auth decisions through the draft tables to confirm they match assessor outcomes.
Agree the SLA and co-pay language with the business and record the protocol source in Annotations.
4
4
The benefits
The benefits
The benefits
Members get answers in hours, not days - routine requests approve within the SLA automatically.
Assessor time is protected - human judgement is spent only where the model defers.
Consistent, fair outcomes - identical requests are treated identically, with the rule trail to prove it.
Clean data for cost control - every decision is structured, so leakage and utilisation become measurable.
5
5
Next steps: what this unlocks
Next steps: what this unlocks
Next steps: what this unlocks
Real-time provider portal - let clinics submit a code and receive an instant pre-auth decision.
AI-assisted exceptions - route “Manual review” cases to an AI assistant that drafts a recommendation for the assessor to confirm.
Expand the rule set - add more procedures, sub-limits and exclusions as new rows without re-engineering.
Fraud & abuse signals - reuse the same decision pattern to flag unusual claiming behaviour for review.
Algorithmic Commercial Credit Decisioning
Tier-1 bank · commercial borrower · HK$ facility · HKMA model-risk governance
DECISION REQUIREMENTS DIAGRAM

BUSINESS RULES DECISION TABLES

Algorithmic Commercial Credit Decisioning
Tier-1 bank · commercial borrower · HK$ facility · HKMA model-risk governance
DECISION REQUIREMENTS DIAGRAM
BUSINESS RULES DECISION TABLES
Algorithmic Commercial Credit Decisioning
Tier-1 bank · commercial borrower · HK$ facility · HKMA model-risk governance
DECISION REQUIREMENTS DIAGRAM
BUSINESS RULES DECISION TABLES
HOW THIS MODEL WORKS - IN PLAIN ENGLISH
HOW THIS MODEL WORKS - IN PLAIN ENGLISH
1
1
How the flow works
How the flow works
How the flow works
Read the diagram from the bottom up. We collect four facts about a commercial borrower: the narrative text of their SEC 10-K filing, their audited financial statements, the Basel IV risk weight for the exposure, and the size of the facility requested. Two are structured numbers; one is free-form language a human normally has to read.
The 10-K text flows first into a deliberately isolated decision, AI Sentiment Ingestion. A financial LLM reads the filing and extracts supply-chain risk language, but it is not allowed to speak freely: the decision table forces its answer into a closed vocabulary, Low, Elevated or Severe, and only accepts it when the model’s own confidence clears 0.80. Anything ambiguous, off-vocabulary or low-confidence is routed to a human analyst, never passed downstream. This is the firewall an HKMA examiner looks for: the probabilistic component can inform but can never decide.
That clean, bounded risk band, together with the deterministic flag from Assess Capital Adequacy (a pure Basel IV calculation on CET1 and RWA density), flows up into Deterministic Credit Approval. Here the outcome is fixed logic: a Severe band or a failed capital check declines automatically; a strong DSCR with a Low band auto-approves; everything else approves with a monitoring covenant. The credit decision is therefore fully explainable and reproducible, even though one of its inputs began life as unstructured language.
2
2
Who does what? The Roles & Interaction
Who does what? The Roles & Interaction
Who does what? The Roles & Interaction
The design maps onto the HKMA’s three-lines-of-defence and model-risk-management expectations: the AI is a tool owned and validated by humans, never an autonomous approver.
The design maps onto the HKMA’s three-lines-of-defence and model-risk-management expectations: the AI is a tool owned and validated by humans, never an autonomous approver.
The design maps onto the HKMA’s three-lines-of-defence and model-risk-management expectations: the AI is a tool owned and validated by humans, never an autonomous approver.
Credit Officer (1st line): Owns the lending policy encoded in Deterministic Credit Approval, the DSCR cut-offs and decline triggers. Works only the refer and covenant cases.
Credit Officer (1st line): Owns the lending policy encoded in Deterministic Credit Approval, the DSCR cut-offs and decline triggers. Works only the refer and covenant cases.
Credit Officer (1st line): Owns the lending policy encoded in Deterministic Credit Approval, the DSCR cut-offs and decline triggers. Works only the refer and covenant cases.
Model Risk Management (2nd line): Owns the guardrail in AI Sentiment Ingestion, the confidence floor, the closed vocabulary, and the validation evidence the regulator inspects.
Model Risk Management (2nd line): Owns the guardrail in AI Sentiment Ingestion, the confidence floor, the closed vocabulary, and the validation evidence the regulator inspects.
Model Risk Management (2nd line): Owns the guardrail in AI Sentiment Ingestion, the confidence floor, the closed vocabulary, and the validation evidence the regulator inspects.
Data Science / AI Engineering: Builds and monitors the LLM but cannot change a credit threshold; the probabilistic/deterministic boundary is enforced in the model itself.
Data Science / AI Engineering: Builds and monitors the LLM but cannot change a credit threshold; the probabilistic/deterministic boundary is enforced in the model itself.
Data Science / AI Engineering: Builds and monitors the LLM but cannot change a credit threshold; the probabilistic/deterministic boundary is enforced in the model itself.
Finance / Capital Management: Owns the Basel IV parameters in Assess Capital Adequacy, the CET1 floor and RWA density caps.
Finance / Capital Management: Owns the Basel IV parameters in Assess Capital Adequacy, the CET1 floor and RWA density caps.
Finance / Capital Management: Owns the Basel IV parameters in Assess Capital Adequacy, the CET1 floor and RWA density caps.
Internal Audit (3rd line): Reads the logged decision trail to prove the AI never made a credit call on its own.
Internal Audit (3rd line): Reads the logged decision trail to prove the AI never made a credit call on its own.
Internal Audit (3rd line): Reads the logged decision trail to prove the AI never made a credit call on its own.
3
3
How do we build it? The Elicitation Process
How do we build it? The Elicitation Process
How do we build it? The Elicitation Process
We separate the two kinds of knowledge, judgemental and regulatory, and capture each at its source:
We separate the two kinds of knowledge, judgemental and regulatory, and capture each at its source:
We separate the two kinds of knowledge, judgemental and regulatory, and capture each at its source:
Workshop with senior credit officers to surface the real approve/decline thresholds they apply, then write them as deterministic rows.
Work with Model Risk Management to set the AI guardrail: the confidence floor, the permitted output enum and the fallback-to-human path.
Map every capital rule to the Basel IV framework and HKMA Banking (Capital) Rules so the numbers trace to regulation, not opinion.
Replay historic credit files through the draft tables to confirm they reproduce the bank’s actual decisions before go-live.
4
4
The benefits
The benefits
The benefits
Auditable AI - the LLM informs but cannot decide; every credit outcome is reproducible from the deterministic tables alone.
Zero hallucination risk - out-of-vocabulary or low-confidence model output is rejected at the boundary, never consumed by the credit rule.
Faster commercial underwriting - analysts stop reading every 10-K end to end; they review only the cases the guardrail escalates.
Regulator-ready - the model-risk separation is exactly the control the HKMA SPM on model risk and AI governance expects to see.
5
5
Next steps: what this unlocks
Next steps: what this unlocks
Next steps: what this unlocks
Validation harness - wrap the deterministic tables in an automated back-test so MRM can re-validate on every model update.
Extend the ingestion - add covenant-breach and litigation-risk extraction as further bounded inputs without touching the credit logic.
Portfolio-level view - because every decision is structured, concentration and supply-chain risk aggregate across the book.
Straight-through lending - once confidence is proven, widen the auto-approve band for the lowest-risk, best-capitalised exposures.
SFC Type 9 Pre-Trade Compliance Gate
SFC Type 9 multi-family office · tokenised RWA trade signal · pre-trade gate
DECISION REQUIREMENTS DIAGRAM

BUSINESS RULES DECISION TABLES

SFC Type 9 Pre-Trade Compliance Gate
SFC Type 9 multi-family office · tokenised RWA trade signal · pre-trade gate
DECISION REQUIREMENTS DIAGRAM
BUSINESS RULES DECISION TABLES
SFC Type 9 Pre-Trade Compliance Gate
SFC Type 9 multi-family office · tokenised RWA trade signal · pre-trade gate
DECISION REQUIREMENTS DIAGRAM
BUSINESS RULES DECISION TABLES
HOW THIS MODEL WORKS - IN PLAIN ENGLISH
HOW THIS MODEL WORKS - IN PLAIN ENGLISH
1
1
How the flow works
How the flow works
How the flow works
Read from the bottom up. An automated trade signal arrives for a high-risk asset class, a tokenised real-world asset or a complex derivative, carrying its asset class and notional size. Around it we hold three reference facts: the client mandate, the asset-segregation ledger, and the market liquidity of the instrument.
Before a single order reaches the market, the signal passes three independent deterministic gates. Check Mandate Alignment confirms the asset class is on that client’s permitted list and within the per-ticket limit. Check Asset Segregation confirms the trade settles into the client’s own ring-fenced sub-account and that no client capital is being commingled. Check Liquidity Threshold confirms the notional is small enough relative to average daily volume to be exited cleanly.
All three results flow up into Determine Pre-Trade Outcome. Only if every gate returns true is the order released straight through to the market. If any one fails, the trade is blocked and automatically escalated to the Responsible Officer for a documented decision, the order never executes silently. For the example signal in a tokenised RWA that breaches the mandate whitelist, the gate blocks and routes to the RO, with the full reason logged for the SFC.
2
2
Who does what? The Roles & Interaction
Who does what? The Roles & Interaction
Who does what? The Roles & Interaction
The model formalises the SFC Type 9 control environment, where the Responsible Officer is personally accountable and asset segregation is non-negotiable.
The model formalises the SFC Type 9 control environment, where the Responsible Officer is personally accountable and asset segregation is non-negotiable.
The model formalises the SFC Type 9 control environment, where the Responsible Officer is personally accountable and asset segregation is non-negotiable.
Portfolio Manager / Dealer: Generates or approves the trade signal. The gate tells them instantly whether an order can proceed or is held.
Portfolio Manager / Dealer: Generates or approves the trade signal. The gate tells them instantly whether an order can proceed or is held.
Portfolio Manager / Dealer: Generates or approves the trade signal. The gate tells them instantly whether an order can proceed or is held.
Responsible Officer (RO): Named explicitly in the output, every blocked trade routes to them for a recorded override or rejection, satisfying personal SFC accountability.
Responsible Officer (RO): Named explicitly in the output, every blocked trade routes to them for a recorded override or rejection, satisfying personal SFC accountability.
Responsible Officer (RO): Named explicitly in the output, every blocked trade routes to them for a recorded override or rejection, satisfying personal SFC accountability.
Compliance: Owns the gate rules, the mandate whitelists, the segregation logic, the liquidity ratio, as editable, version-controlled table rows.
Compliance: Owns the gate rules, the mandate whitelists, the segregation logic, the liquidity ratio, as editable, version-controlled table rows.
Compliance: Owns the gate rules, the mandate whitelists, the segregation logic, the liquidity ratio, as editable, version-controlled table rows.
Operations / Settlement: Owns the asset-segregation ledger that drives Check Asset Segregation; their account mapping feeds the decision directly.
Operations / Settlement: Owns the asset-segregation ledger that drives Check Asset Segregation; their account mapping feeds the decision directly.
Operations / Settlement: Owns the asset-segregation ledger that drives Check Asset Segregation; their account mapping feeds the decision directly.
Internal Audit / SFC Examiner: Reads a complete pre-trade decision log proving no order bypassed the controls.
Internal Audit / SFC Examiner: Reads a complete pre-trade decision log proving no order bypassed the controls.
Internal Audit / SFC Examiner: Reads a complete pre-trade decision log proving no order bypassed the controls.
3
3
How do we build it? The Elicitation Process
How do we build it? The Elicitation Process
How do we build it? The Elicitation Process
We turn the firm’s compliance manual and the RO’s judgement into explicit, testable pre-trade rules:
We turn the firm’s compliance manual and the RO’s judgement into explicit, testable pre-trade rules:
We turn the firm’s compliance manual and the RO’s judgement into explicit, testable pre-trade rules:
Workshop with the Responsible Officer and Compliance to capture the real mandate, segregation and liquidity limits applied today.
Map each control to its source, the SFC Code of Conduct and the Securities and Futures (Client Securities) Rules, and each client’s investment management agreement.
Encode client mandates as structured whitelists and ticket limits, reviewed and signed off per client.
Replay recent trades through the draft gates to confirm they would have caught the breaches Compliance expects.
4
4
The benefits
The benefits
The benefits
Breaches stopped before execution - mandate, commingling and liquidity violations are caught pre-trade, not discovered in a post-trade review.
RO accountability built in - every exception routes to the Responsible Officer by design, not by manual chasing.
100% auditability - each signal produces a logged pass/block record with the exact rule that fired.
Consistent across clients - the same gate runs identically for every mandate, removing dealer-by-dealer discretion.
5
5
Next steps: what this unlocks
Next steps: what this unlocks
Next steps: what this unlocks
Real-time OMS integration - wire the gate into the order-management system so blocks are enforced at the point of execution.
Per-client dashboards - surface mandate headroom and segregation status live to PMs and the RO.
Extend the asset universe - add new tokenised and private-market instruments as additional rule rows without re-engineering.
Automated regulatory reporting - feed the structured decision logs straight into SFC audit and breach-reporting workflows.
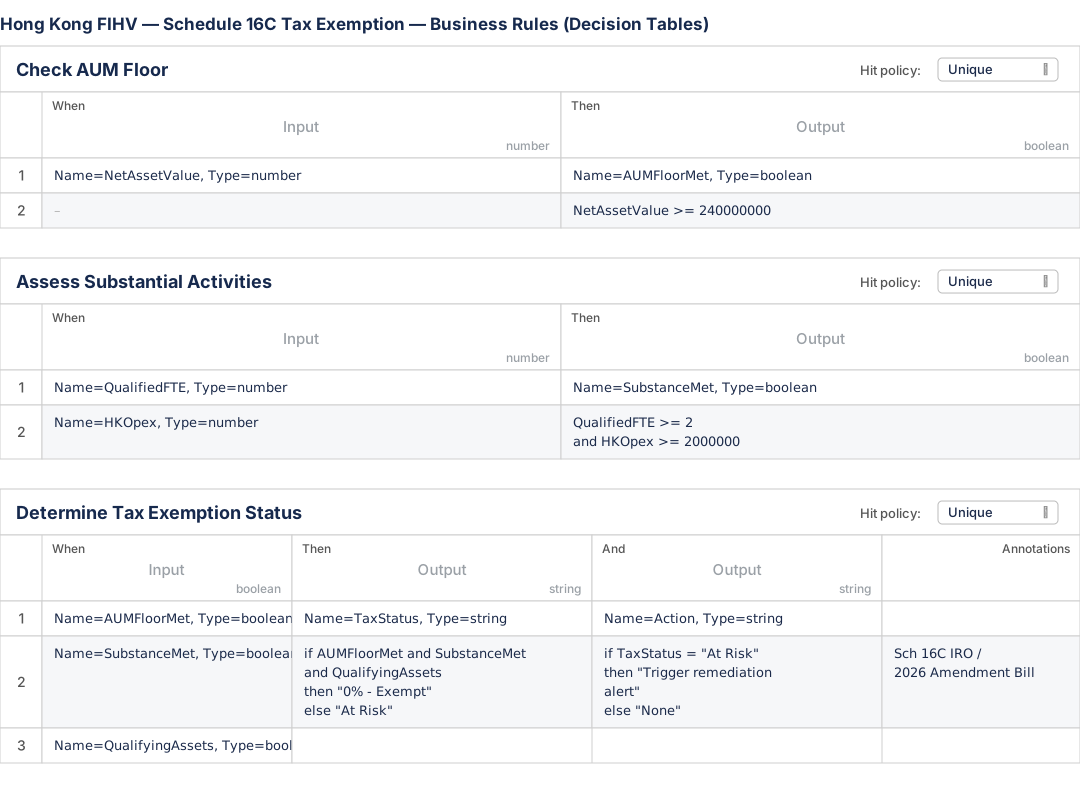
Hong Kong FIHV — Schedule 16C Tax Exemption
Single-family office · Family-owned Investment Holding Vehicle · 0% profits-tax concession
DECISION REQUIREMENTS DIAGRAM

BUSINESS RULES DECISION TABLES
Hong Kong FIHV — Schedule 16C Tax Exemption
Single-family office · Family-owned Investment Holding Vehicle · 0% profits-tax concession
DECISION REQUIREMENTS DIAGRAM
BUSINESS RULES DECISION TABLES
Hong Kong FIHV — Schedule 16C Tax Exemption
Single-family office · Family-owned Investment Holding Vehicle · 0% profits-tax concession
DECISION REQUIREMENTS DIAGRAM
BUSINESS RULES DECISION TABLES
HOW THIS MODEL WORKS - IN PLAIN ENGLISH
HOW THIS MODEL WORKS - IN PLAIN ENGLISH
1
1
How the flow works
How the flow works
How the flow works
Read from the bottom up. For a Hong Kong Family-owned Investment Holding Vehicle (FIHV) we continuously monitor four facts: the vehicle’s net asset value, its Hong Kong operating expenditure, its number of qualified full-time employees, and whether its holdings are qualifying assets. These are exactly the conditions the profits-tax concession depends on.
Two of them feed dedicated decisions. Check AUM Floor confirms net assets stay at or above the HK$240 million threshold. Assess Substantial Activities confirms the substance test is met, at least two qualified full-time employees in Hong Kong and at least HK$2 million of operating expenditure incurred locally. Keeping these as separate nodes means each condition can be monitored and evidenced independently.
Both results, with the qualifying-asset check, flow into Determine Tax Exemption Status. While every condition holds, the status returns 0%, Exempt and nothing happens. The moment any one fails, AUM dips below the floor, headcount drops, expenditure falls short, the status flips to At Risk and an automated remediation alert fires to the family office before the year-end assessment, giving time to cure the breach rather than discovering it after the tax shield has already evaporated.
2
2
Who does what? The Roles & Interaction
Who does what? The Roles & Interaction
Who does what? The Roles & Interaction
The model turns a once-a-year filing scramble into a continuous, owned control, mapping the Inland Revenue regime onto the people who can act on it.
The model turns a once-a-year filing scramble into a continuous, owned control, mapping the Inland Revenue regime onto the people who can act on it.
The model turns a once-a-year filing scramble into a continuous, owned control, mapping the Inland Revenue regime onto the people who can act on it.
Family Office Principal: Owns the outcome, the alert lands with them while there is still time to add substance or top up assets before the breach crystallises.
Family Office Principal: Owns the outcome, the alert lands with them while there is still time to add substance or top up assets before the breach crystallises.
Family Office Principal: Owns the outcome, the alert lands with them while there is still time to add substance or top up assets before the breach crystallises.
Tax Advisor: Owns the rules in Determine Tax Exemption Status, the thresholds and definitions drawn from Schedule 16C and the 2026 amendment.
Tax Advisor: Owns the rules in Determine Tax Exemption Status, the thresholds and definitions drawn from Schedule 16C and the 2026 amendment.
Tax Advisor: Owns the rules in Determine Tax Exemption Status, the thresholds and definitions drawn from Schedule 16C and the 2026 amendment.
Finance / Operations: Owns the substance inputs, tracks HK operating expenditure and full-time headcount that drive Assess Substantial Activities.
Finance / Operations: Owns the substance inputs, tracks HK operating expenditure and full-time headcount that drive Assess Substantial Activities.
Finance / Operations: Owns the substance inputs, tracks HK operating expenditure and full-time headcount that drive Assess Substantial Activities.
Investment Team: Owns the qualifying-asset and AUM inputs; their allocation decisions feed Check AUM Floor directly.
Investment Team: Owns the qualifying-asset and AUM inputs; their allocation decisions feed Check AUM Floor directly.
Investment Team: Owns the qualifying-asset and AUM inputs; their allocation decisions feed Check AUM Floor directly.
Company Secretary / Compliance: Holds the evidenced, time-stamped record that the concession conditions were met throughout the year.
Company Secretary / Compliance: Holds the evidenced, time-stamped record that the concession conditions were met throughout the year.
Company Secretary / Compliance: Holds the evidenced, time-stamped record that the concession conditions were met throughout the year.
3
3
How do we build it? The Elicitation Process
How do we build it? The Elicitation Process
How do we build it? The Elicitation Process
We translate the statutory conditions and the family’s own structure into explicit, monitorable rules:
We translate the statutory conditions and the family’s own structure into explicit, monitorable rules:
We translate the statutory conditions and the family’s own structure into explicit, monitorable rules:
Workshop with the family’s tax advisor to capture every condition of the FIHV concession and how it applies to this structure.
Map each rule to its source, Schedule 16C of the Inland Revenue Ordinance and the 2026 Inland Revenue (Amendment) Bill , so every threshold is traceable.
Connect the inputs to live data, the administrator’s NAV, the bookkeeping system’s HK expenditure, the HR record of full-time staff.
Agree the alert thresholds with the principal so warnings fire with enough runway to remediate before year-end.
4
4
The benefits
The benefits
The benefits
The tax shield is defended continuously - conditions are checked all year, not reconstructed at filing time.
Early warning, time to cure - a drift below any threshold triggers an alert while remediation is still possible.
Evidenced compliance - a logged trail proves substance and AUM were maintained, ready for the Inland Revenue Department.
Succession-ready - the conditions sustaining the 0% rate are documented and monitorable across generations, not held in one advisor’s head.
5
5
Next steps: what this unlocks
Next steps: what this unlocks
Next steps: what this unlocks
Live data feeds - connect NAV, accounting and HR systems so the checks run automatically each period.
Scenario testing - model the tax impact of a planned redemption or restructuring before it breaches a threshold.
Multi-entity roll-up - extend the same pattern across several FIHVs or special-purpose entities in the structure.
Succession dashboard - give the next generation a clear, ongoing view of the conditions that preserve the family’s tax position.
Alpha Generation — Alternative-Data Valuation Trigger
Quant fund · Glassdoor & X sentiment · automated exposure management
DECISION REQUIREMENTS DIAGRAM

BUSINESS RULES DECISION TABLES

Alpha Generation — Alternative-Data Valuation Trigger
Quant fund · Glassdoor & X sentiment · automated exposure management
DECISION REQUIREMENTS DIAGRAM
BUSINESS RULES DECISION TABLES
Alpha Generation — Alternative-Data Valuation Trigger
Quant fund · Glassdoor & X sentiment · automated exposure management
DECISION REQUIREMENTS DIAGRAM
BUSINESS RULES DECISION TABLES
HOW THIS MODEL WORKS - IN PLAIN ENGLISH
HOW THIS MODEL WORKS - IN PLAIN ENGLISH
1
1
How the flow works
How the flow works
How the flow works
Read from the bottom up. We ingest two streams of alternative data that traditional models ignore: Glassdoor employee-sentiment reviews (a leading signal of corporate culture and operational rot) and X / Twitter retail-hype chatter. Alongside them sit the fundamental valuation of the stock and the fund’s current exposure to it.
The two text streams flow into AI Sentiment Scoring, where a financial LLM reads them and produces a single sentiment delta. Crucially, that probabilistic output is caged: the table clamps it to a band of plus or minus 20% and zeroes it out entirely when model confidence is below 0.75. A burst of noise or a hallucinated reading can never move the valuation more than the rules permit, the AI shapes the signal, it does not seize the wheel.
That bounded delta flows into Adjust Intrinsic Value, which scales the analyst’s base DCF target by the sentiment factor. The new target then meets the live market price in Determine Exposure Action: if price has run more than 10% above the sentiment-adjusted intrinsic value, the model returns Reduce Exposure and trims the position to half its limit, automatically, with no manual intervention. For a name like Bloom Energy seeing a culture-sentiment drop and a cooling hype cycle, the target falls, the market price now looks rich, and exposure is cut before the drawdown.
2
2
Who does what? The Roles & Interaction
Who does what? The Roles & Interaction
Who does what? The Roles & Interaction
The model lets quantitative judgement scale across thousands of names while keeping humans in charge of the rules, not the individual trades.
The model lets quantitative judgement scale across thousands of names while keeping humans in charge of the rules, not the individual trades.
The model lets quantitative judgement scale across thousands of names while keeping humans in charge of the rules, not the individual trades.
Portfolio Manager: Owns the action rules in Determine Exposure Action, the over/under-valuation bands and the sizing response. Sets risk appetite, not individual trades.
Portfolio Manager: Owns the action rules in Determine Exposure Action, the over/under-valuation bands and the sizing response. Sets risk appetite, not individual trades.
Portfolio Manager: Owns the action rules in Determine Exposure Action, the over/under-valuation bands and the sizing response. Sets risk appetite, not individual trades.
Quantitative Researcher: Owns the AI guardrail in AI Sentiment Scoring, the clamp band, the confidence floor, and the mapping from text to delta.
Quantitative Researcher: Owns the AI guardrail in AI Sentiment Scoring, the clamp band, the confidence floor, and the mapping from text to delta.
Quantitative Researcher: Owns the AI guardrail in AI Sentiment Scoring, the clamp band, the confidence floor, and the mapping from text to delta.
Risk Management: Owns the exposure limits the action table trims toward, and monitors that the automated sizing stays within mandate.
Risk Management: Owns the exposure limits the action table trims toward, and monitors that the automated sizing stays within mandate.
Risk Management: Owns the exposure limits the action table trims toward, and monitors that the automated sizing stays within mandate.
Data Engineering: Owns the alternative-data pipelines (Glassdoor, social) feeding the model, but cannot alter a trading threshold.
Data Engineering: Owns the alternative-data pipelines (Glassdoor, social) feeding the model, but cannot alter a trading threshold.
Data Engineering: Owns the alternative-data pipelines (Glassdoor, social) feeding the model, but cannot alter a trading threshold.
Compliance: Holds the logged trail showing every automated exposure change and the bounded signal that justified it.
Compliance: Holds the logged trail showing every automated exposure change and the bounded signal that justified it.
Compliance: Holds the logged trail showing every automated exposure change and the bounded signal that justified it.
3
3
How do we build it? The Elicitation Process
How do we build it? The Elicitation Process
How do we build it? The Elicitation Process
We turn the PM’s investment thesis and the firm’s risk limits into explicit, bounded rules:
We turn the PM’s investment thesis and the firm’s risk limits into explicit, bounded rules:
We turn the PM’s investment thesis and the firm’s risk limits into explicit, bounded rules:
Workshop with the portfolio manager to capture how alternative-data signals should, and should not, move a position.
Set the AI guardrail with Quant Research: the clamp band, the confidence floor, and the decay applied to stale signals.
Calibrate the valuation and action thresholds against historic episodes where sentiment led price, to confirm the rules would have helped, not hurt.
Agree hard exposure limits with Risk so the automation can never breach mandate, however strong the signal.
4
4
The benefits
The benefits
The benefits
Edge from data others discard - culture and hype signals become a structured, tradable input.
Bounded, not unbounded, AI - the clamp and confidence floor mean a noisy or hallucinated reading cannot blow up a position.
Emotion-free execution - exposure is cut on the rules, not on the PM’s nerve, removing behavioural drag.
Fully logged - every automated trim is traceable to the exact signal and rule that triggered it.
5
5
Next steps: what this unlocks
Next steps: what this unlocks
Next steps: what this unlocks
Broaden the signal set - add app-download, hiring-velocity and supply-chain data as further bounded inputs.
Per-name confidence tuning - let the clamp band widen for names where the signal has proven predictive.
Live paper-trading - run the engine in shadow mode and measure signal-to-alpha before committing capital.
Cross-asset reuse - apply the same probabilistic-to-deterministic pattern to credit and commodity books.
"These structured rules (exportable in FEEL/DMN or structured JSON) can be directly ingested into InvestLM or your preferred financial LLM to deliver explainable, domain-aware decisions while maintaining full auditability and human oversight.
"These structured rules (exportable in FEEL/DMN or structured JSON) can be directly ingested into InvestLM or your preferred financial LLM to deliver explainable, domain-aware decisions while maintaining full auditability and human oversight.
"These structured rules (exportable in FEEL/DMN or structured JSON) can be directly ingested into InvestLM or your preferred financial LLM to deliver explainable, domain-aware decisions while maintaining full auditability and human oversight.
Structured mapping supports PDPO principles of data minimisation, purpose limitation, and accountability when feeding AI systems."
Structured mapping supports PDPO principles of data minimisation, purpose limitation, and accountability when feeding AI systems."
Structured mapping supports PDPO principles of data minimisation, purpose limitation, and accountability when feeding AI systems."
Underwriting is logic.
It should be documented like logic.
Underwriting is logic.
It should be documented like logic.
Underwriting is logic.
It should be documented like logic.
Every rule above exists in underwriting manuals, underwriting judgment, or exception records. Most firms have it in at least two of those three places, none of which feed an AI system.
Every rule above exists in underwriting manuals, underwriting judgment, or exception records. Most firms have it in at least two of those three places, none of which feed an AI system.
Every rule above exists in underwriting manuals, underwriting judgment, or exception records. Most firms have it in at least two of those three places, none of which feed an AI system.
We extract all three and structure them into a single, auditable framework.
We extract all three and structure them into a single, auditable framework.
We extract all three and structure them into a single, auditable framework.